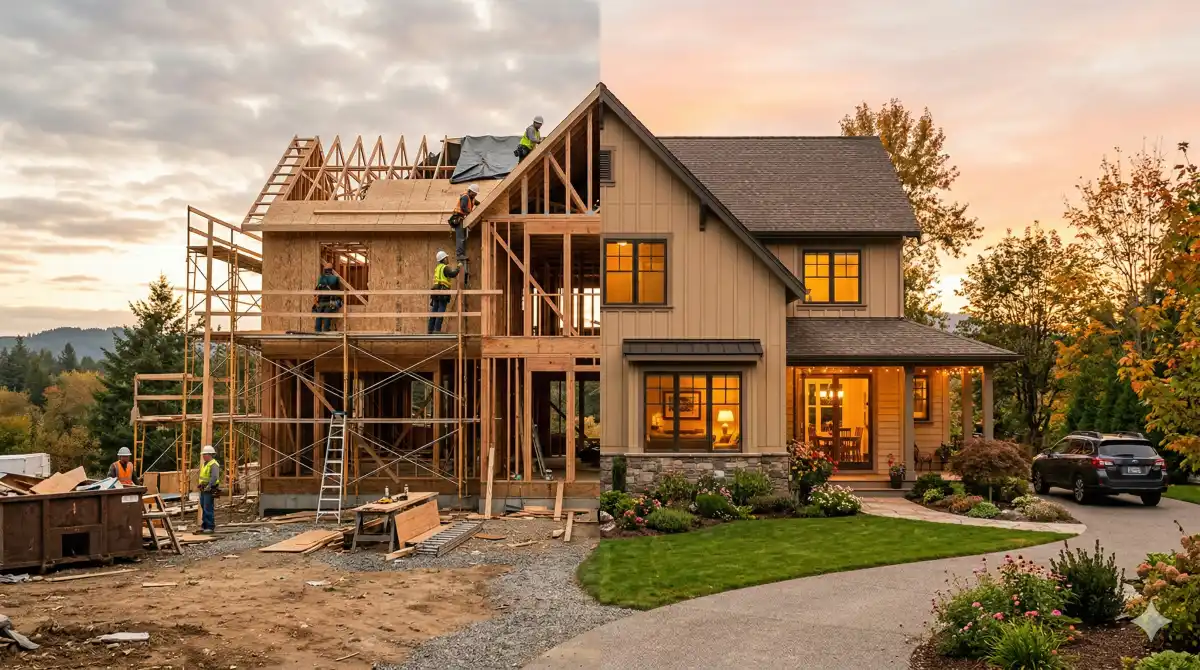
Case Study: First-Time Builder Constructs $485K Custom Home in Austin Suburbs
How Sarah and Mike Martinez navigated the construction loan process as first-time builders to create their dream 2,800 sq ft home in the Austin metro area.
Project Overview
Location:
Pflugerville, TX (Austin metro)
Home Size:
2,800 sq ft, 4 bed / 3 bath
Total Project Cost:
$485,000
Timeline:
14 months (planning to move-in)
Loan Type:
Construction-to-Permanent
Final Outcome:
Completed on budget, 2 weeks early
The Borrowers
Sarah and Mike Martinez
Young professionals relocating from California to Texas for work. Sarah (32) works in tech, Mike (34) is an engineer. Combined household income $175,000.
Financial Profile
- • Credit scores: 740 (Sarah), 755 (Mike)
- • Combined income: $175,000/year
- • Existing debts: $450/mo car payment, $120/mo student loans
- • Down payment: $125,000 (25%)
- • Reserves: $45,000
Experience Level
- • First-time home builders
- • Previously owned condo in California
- • No construction experience
- • Did extensive research before starting
- • Consulted with 3 real estate agents
Project Goals
- Build custom home tailored to their needs (open floor plan, home offices for both)
- Stay under $500K total cost including land
- Energy efficiency to minimize ongoing utility costs
- Complete within 12 months to minimize double-housing costs
- Good resale value for future flexibility
The Journey: Phase by Phase
Research & Planning (Months 1-3)
Sarah and Mike spent three months researching before taking any action. They attended builder home tours, interviewed contractors, and educated themselves about construction financing.
Key Actions Taken:
- • Attended 12 builder open houses to understand quality and styles
- • Interviewed 7 contractors, got detailed bids from 4
- • Got pre-qualified with 3 lenders (chose UFCU)
- • Spent weekends driving neighborhoods to find ideal lot location
- • Created detailed wish list and must-have features
- • Established realistic budget with 15% contingency
Outcome: Found perfect 0.25-acre lot in Pflugerville for $85,000. Selected experienced contractor with excellent references and competitive bid.
Design & Plans (Months 4-5)
Worked with contractor's architect to design custom floor plan. Modified stock plan to include two home offices, larger kitchen, and energy-efficient features.
Design Specifications:
Main Level (1,900 sq ft):
- • Open concept living/kitchen/dining
- • Master suite with walk-in closet
- • Home office #1
- • Guest bedroom
- • 2.5 bathrooms
Second Level (900 sq ft):
- • Two bedrooms
- • Full bathroom
- • Home office #2
- • Bonus room/flex space
Challenge: Initial design came in $35,000 over budget. Made strategic cuts: reduced from 3-car to 2-car garage, simplified roof line, used standard window sizes. Solution brought project back on budget.
Loan Application (Months 6-7)
Applied for construction-to-permanent loan with UFCU (University Federal Credit Union) based on competitive rates and strong reviews.
Financial Details:
Loan Terms Secured:
- • Construction rate: 7.75% (12-month construction period)
- • Permanent rate: 7.125% (30-year fixed, locked at application)
- • Interest-only payments during construction
- • No pre-payment penalty
- • Single closing (construction-to-permanent)
Success Factor: Strong credit scores, stable employment, and well-documented plans led to smooth 7-week approval process. UFCU's membership rates were 0.375% lower than competing banks.
Construction Phase (Months 8-18)
Construction began in February and progressed through fall, taking advantage of good weather. Project stayed remarkably close to schedule despite a few minor challenges.
Months 8-9: Foundation & Framing
On ScheduleSite prep, foundation pour, framing complete. First draw: $120,000. Monthly interest payment: $775/month.
Months 10-12: Exterior & Rough-Ins
Minor DelayRoofing, windows, exterior complete. HVAC, plumbing, electrical rough-in. Second draw: $145,000. Monthly interest payment: $1,725/month.
Challenge: 2-week delay for custom windows. Impact: Minimal - contractor adjusted schedule to work on other items.
Months 13-15: Interior Finishing
On ScheduleDrywall, flooring, cabinetry, interior paint, trim. Third draw: $95,000. Monthly interest payment: $2,425/month.
Months 16-17: Final Touches & Inspection
Ahead of ScheduleFixtures, appliances, landscaping, final inspection. Final draw: $40,500. Total drawn: $400,500.
Success: Contractor finished 2 weeks early due to good weather and efficient subcontractor scheduling.
Unexpected Challenge: Foundation Issue
During excavation, discovered rock layer requiring more extensive blasting than anticipated. Additional cost: $8,500.
Resolution: Covered by contingency fund. Made minor adjustments to landscaping budget to stay within overall budget.
Completion & Move-In (Month 18)
Final inspection passed, certificate of occupancy issued. Loan automatically converted from construction to permanent financing. Moved in on schedule.
Final Financial Summary:
Key Success Factors
What Went Right:
- ✓ Thorough upfront research and planning
- ✓ Realistic budget with adequate contingency
- ✓ Excellent contractor selection
- ✓ Strong financial profile for loan approval
- ✓ Construction-to-permanent loan locked rates
- ✓ Regular communication with all parties
- ✓ Flexible with non-critical design elements
- ✓ Weekly site visits to monitor progress
Lessons Learned:
- • Site evaluation is critical (rock issue)
- • 15% contingency was just right
- • Credit union rates beat big banks
- • Good contractor worth premium price
- • Weekly site visits prevented issues
- • Standard materials reduce costs significantly
- • Construction timeline flexibility important
- • Document everything in writing
Outcome & Satisfaction
Project Outcomes
Total Timeline
Planning to move-in
Final Cost per Sq Ft
Below Austin metro average
Monthly Payment
Lower than renting equivalent
Sarah & Mike's Reflection (6 months after move-in):
"Building our home was challenging but incredibly rewarding. The key was doing our homework upfront— we spent three months researching before committing to anything. Finding a great contractor made all the difference. Yes, we paid a bit more than the lowest bid, but his quality, communication, and reliability were worth it. The construction-to-permanent loan from UFCU saved us money with their membership rates and eliminated the stress of finding permanent financing later."
"Our home is exactly what we wanted—the two home offices have been perfect for remote work, and the energy efficiency features are already saving us $150-200/month compared to what friends pay in similar-sized homes. After appraisal, we have $75,000 in instant equity, which makes the effort worthwhile."
"Would we do it again? Absolutely. Would we do anything differently? We'd start the permitting process even earlier, and we'd budget a bit more for landscaping—we had to scale back there to stay on budget. But overall, we're thrilled with the outcome and glad we built instead of buying existing."
Takeaways for Prospective Builders
Before You Start
- • Spend 2-3 months researching thoroughly
- • Interview multiple contractors, check references
- • Get pre-qualified to understand what you can afford
- • Budget 15-20% contingency for unexpected costs
- • Understand realistic timelines for your area
- • Consider resale value in design decisions
During Construction
- • Visit site weekly to catch issues early
- • Maintain regular communication with contractor
- • Document everything in writing
- • Be flexible on non-critical items
- • Keep good records for lender draws
- • Stay engaged but trust your professionals
Conclusion
Sarah and Mike's success demonstrates that first-time builders can navigate the construction loan process successfully with proper preparation, realistic expectations, and good professional partners. Their story highlights the importance of thorough research, adequate budgeting, and selecting experienced contractors.
Ready to start your own construction journey? Use our Construction Loan Calculator to estimate your project costs and payments, and review our qualification guide to prepare your application.